FHA Manufactured Home Foundation Requirements
In this guide
For an FHA Title II mortgage on a manufactured home, a permanent foundation meeting the applicable requirements is part of property eligibility. A preapproval for the borrower does not replace the property documentation. Ask your lender for the written foundation condition before ordering an inspection or choosing repairs.
Have the lender’s request? Request an FHA foundation inspection with the property address, the condition, and your report deadline.
Is an FHA structural inspection the same as a foundation certification?
Usually, yes. When a lender asks for an "FHA structural inspection" or an "FHA structural report" on a manufactured home, it most often means the engineer's foundation certification. On a home that has been moved, added onto or repaired, the same words can ask for more. Copy the condition word for word, and see how to order a HUD engineering report for the other names it goes by.
What does FHA require for the foundation report?
HUD’s current Single Family Housing Policy Handbook describes a permanent-foundation requirement tied to the Permanent Foundations Guide for Manufactured Housing. It calls for certification by an engineer or architect licensed or registered in the state where the home is located.
The handbook also describes circumstances in which a foundation certification from a previous FHA-insured mortgage may be used, subject to its conditions. If the appraisal identifies additions or alterations, the lender must ensure they are addressed in the certification. Your lender should determine which documentation applies to the current file. See HUD’s Single Family Housing Policy Handbook, revised August 2026.
What does the engineer check?
The scope depends on the condition in the file, but an FHA foundation inspection typically looks at:
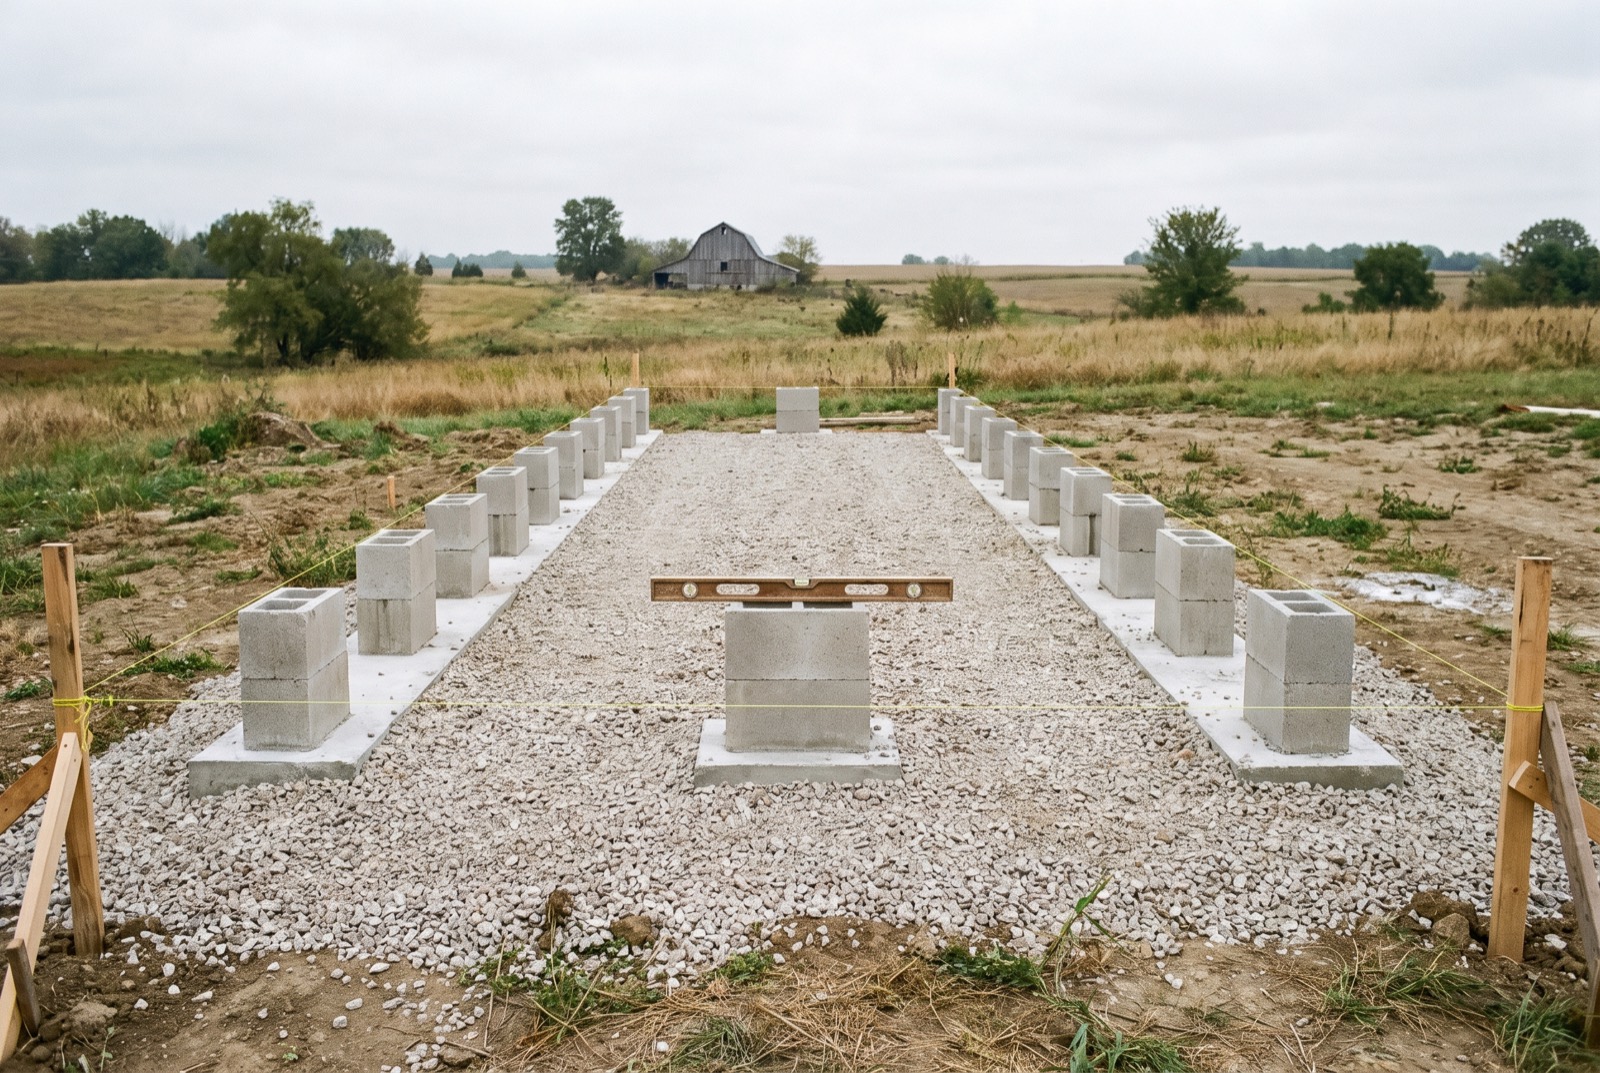
- How the home is supported: the footings, piers or perimeter wall under it.
- How the home is anchored and tied to that support.
- The conditions that can be reached in the crawl space or under the home.
- Additions, porches or decks attached to the home, and any changes the appraisal noted.
- The HUD label and data plate, so the report identifies the right home.
Clear the way to the crawl space access before the visit. If skirting has to come off to see under the home, say so when you book.
Does a home need a full basement?
Do not identify a compliant foundation by its appearance or by one feature such as a basement. The engineering question concerns the applicable foundation criteria and the property’s actual supporting system. Skirting, an enclosed perimeter, or a long installation history does not by itself establish compliance.
Our PFGMH certification guide explains the terminology and what to send with a foundation-report request. A property-specific inspection is the starting point when the lender requires new engineering documentation.
What if the foundation needs work?
Ask for the findings and clarify the next step before arranging repairs. Depending on the condition and the assignment, further investigation, repair design, completed work, or another review may be needed. Confirm what is included in the engineering quote and what would be additional.
Do not assume that paying for a report guarantees a favorable certification. The engineer’s conclusions depend on the conditions and information reviewed. The lender separately determines whether the resulting documentation satisfies its requirement.
Which documents should you gather?
- The property address and state.
- The lender’s written foundation condition.
- Any previous engineering certification or report.
- Information about additions, alterations, or foundation repairs.
- Available HUD label and data plate records.
- The access contact and requested report date.
If a record is missing, say so. A missing HUD label can require a records-verification step that is separate from the foundation inspection. Read our HUD label and data plate guide before assuming another engineering report will answer an identification request.
Does the foundation report complete the loan approval?
The foundation report addresses its specified engineering scope. Borrower qualification, appraisal, title, insurance, and other property requirements remain part of the lender’s review. Ask the loan officer what will still be outstanding after the report is delivered.
For title-related questions, the foundation certification versus affixation guide helps explain why those documents need separate attention. Coordinate the engineering appointment with the lender’s review deadline rather than only the planned closing day.
Arrange the inspection your lender needs
We issue FHA foundation certifications in Missouri, Arkansas, Illinois, Kansas, Iowa, Nebraska and Indiana. Review Scapular’s FHA foundation inspection service and service coverage, then request an inspection quote. If you are still preparing the property details, use our manufactured-home inspection checklist.
Have an FHA foundation requirement?
Share your lender’s condition and requested report date. We can discuss the inspection and quote.